

Disability and Income Replacement Insurance
- August 31, 2026
- Posted by: olinsadmin
- Categories: Accident Insurance, Freelancers, Group Health Insurance, Insurance Toronto, Life Insurance Ontario, Life Insurance Toronto, Medical Insurance Ontario
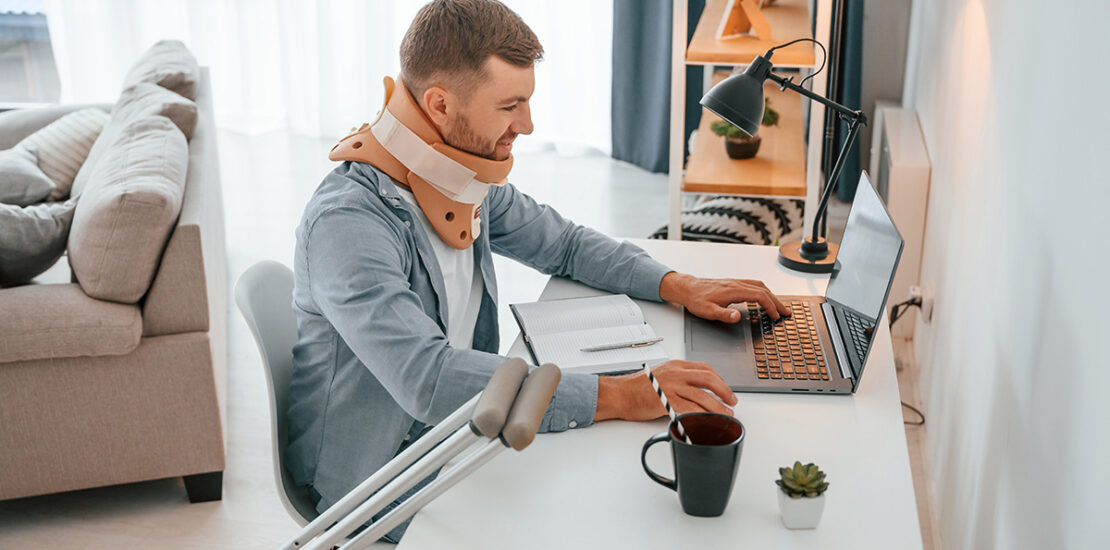
Most people insure their homes, cars and even their phones. But what about the asset that pays for all of them — your ability to earn an income?
An unexpected accident or injury can prevent you from working for weeks, months or even longer. For employees, self-employed professionals, business owners, truck drivers, construction workers and other physically active workers, losing the ability to work can quickly become a financial problem.
That is where disability and income replacement insurance can help.
What Is Disability Income Replacement Insurance?
Disability insurance is designed to provide regular income when a covered disability prevents you from working. Instead of receiving one large payment, eligible claimants generally receive monthly benefits intended to replace part of their lost earnings.
Some simplified-issue disability programs provide monthly benefits ranging from $500 to as much as $6,000, depending on income, occupation and the coverage selected. They may cover disabilities resulting from accidents and soft tissue injuries, with illness protection available as an optional addition.
This can be particularly valuable because government programs or workplace benefits may not replace your entire income. In Canada, long-term disability plans commonly replace approximately 60% to 70% of normal income, although every plan has its own rules and definitions.
Soft Tissue Injuries Matter More Than You May Think
When people hear the word “disability,” they often imagine a catastrophic accident. In reality, an injury does not have to be dramatic to stop someone from doing their job:
- Sprains, strains, tendon injuries and other soft tissue problems can seriously affect your ability to lift, drive, stand, type or perform repetitive movements.
- For a roofer, carpenter, truck driver, dental hygienist, warehouse worker or self-employed contractor, even a seemingly ordinary injury can mean weeks without regular earnings.
That makes soft tissue injury coverage an important feature to investigate when comparing disability insurance.
What about Illness?
Accidents are only part of the picture.
Some simplified disability plans allow applicants to add coverage for disability caused by illness. Eligibility and exclusions vary, so it is important to understand exactly which illnesses are covered, what medical questions must be answered and whether specific conditions are excluded.
The key word is contract. Never assume that “illness coverage” means every possible medical condition will qualify.
No Medical Exam Can Make Applying Easier
Traditional disability insurance underwriting can involve extensive medical information. Simplified-issue options may require only a limited number of health questions and no medical examination, blood test or lengthy questionnaire.
That can make this type of insurance worth investigating for people who want a faster, simpler application process. However, “no medical exam” does not mean “guaranteed approval.” Applicants still need to meet the insurer’s eligibility requirements and answer application questions accurately.
Protection for Self-Employed Canadians
For a salaried employee, becoming disabled creates an income problem. For a business owner, it can create two problems at once: personal income disappears while business bills continue. Rent, utilities, vehicle expenses, maintenance and employee-related costs do not automatically stop because the owner cannot work.
Some disability programs therefore offer business overhead expense insurance, with coverage potentially reaching $6,000 per month. This can be particularly useful for contractors, owner-operator truck drivers, tradespeople and other small-business owners whose businesses depend heavily on their personal ability to work.
Look Beyond the Monthly Benefit
When comparing disability insurance in Canada, don’t look only at the maximum benefit. Ask about the waiting period, benefit period, definition of disability, occupational restrictions, exclusions, partial-disability provisions and whether coverage applies only outside working hours or on a 24-hour basis. Some policies may also include rehabilitation benefits, premium waivers during qualifying disabilities and provisions dealing with recurrent disabilities.
Your Income Deserves Protection Too
We rarely expect an accident on Monday morning or an injury on Friday afternoon. Unfortunately, mortgages, groceries, utilities and other bills continue regardless.
Disability and income replacement insurance cannot prevent an accident or illness. What it can do is create a financial buffer between being temporarily unable to work and watching your savings disappear.
If your lifestyle depends on your paycheque — as most lifestyles do — protecting that income deserves a place in your financial plan.